Business plan for a physical product: what it must include
What a business plan for a physical product must include: demand, unit costs, factory, certifications, channel and cash. A real viability analysis.
A business plan for a physical product is not a 40-page Word file. It is a map of whether you can manufacture, pay, deliver and buy materials again without running out of cash. If the document does not answer that, it is a story.
The gap with a service is brutal. In a service you get paid and then you work. With a physical product you pay the factory, tooling, stock, freight and certifications before you see the customer’s first euro. That is why business viability analysis is not an appendix here. It is the plan.
EY has documented it in industrial products: more than $230 billion tied up in working capital, and a cash conversion cycle that typically exceeds 60 days, versus 25–30 in other industries. Not the idea. The money trapped between buying, producing and getting paid.
What a generic plan leaves out
The usual template (summary, market, team, 5-year P&L) is not enough. A physical product needs, at minimum:
- Evidence of demand, not “the market is large”.
- A real unit cost, including scrap, pack and freight.
- How and where it is made, with tooling and capacity.
- Certifications and barriers to market entry.
- Channel and payment terms.
- Working capital: how much money sleeps in stock and at customs.
Without those six points you can impress a relative. Not a supplier, not a bank, and not yourself in six months.
1. Demand and opportunity
Start with the same work as validating an idea: is anyone looking for this, paying to solve it today, and willing to do it with you?
For a physical product, add volume. Not “there is interest”. How many units, at what price, in which channel, in the first 12 months. In Harvard Business Review, Christensen, Cook and Hall wrote that about 30,000 new consumer products launch each year and more than 90% fail. The plan has to explain why yours is not in that 90%, with category data, not enthusiasm.
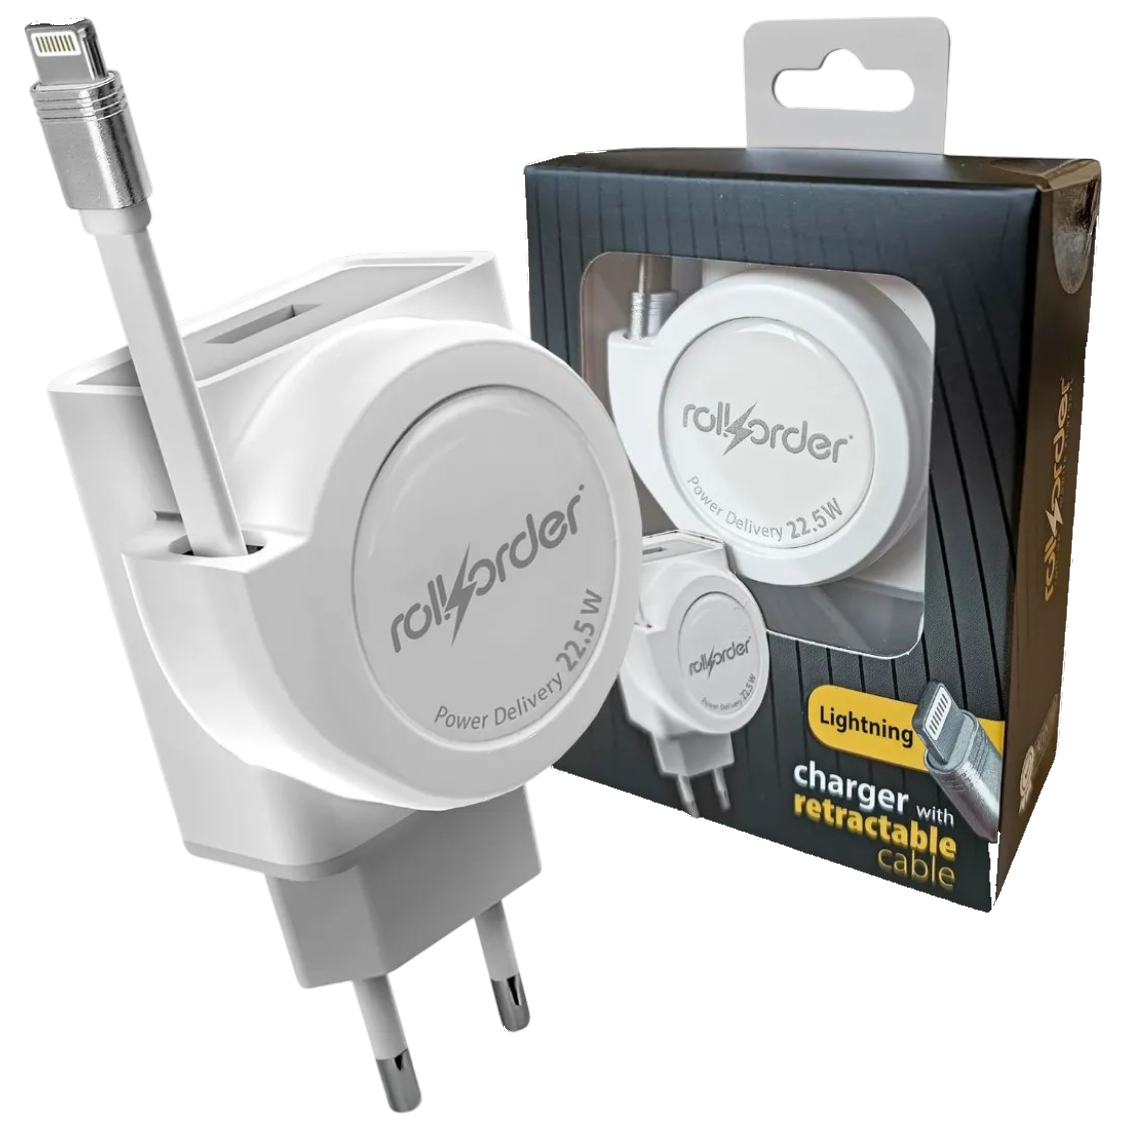
On Roll Order we validated colour and connectors with real Amazon sales data in six countries before producing. That is opportunity analysis. A PowerPoint TAM is not.
2. Unit economics
If you cannot write on one line the product cost landed in your warehouse and the selling price, you do not have a plan. Include:
- Materials (a bill of materials, not a round number).
- Factory labour and overhead.
- Pack, labelling, manuals.
- Freight, duties, insurance.
- Scrap and quality.
- Channel commission. On Amazon Spain, referral fees for most categories sit between 8% and 15%.
That gives contribution margin. From the margin, break-even in units. If covering fixed costs needs a volume the channel will not give you in year 1, the model does not close. Better to learn that in a spreadsheet than in a container.
3. Industrialisation and capacity
Who manufactures, in which country, with what lead time, what minimum order and what mould. Tooling is the hidden cost that surprises people most. So is the jump from prototype to series: what works in 10 units can break at 1,000.
The plan should state installed capacity and realistic year-1 capacity. Assuming 100% of the line from month 1 is the classic error. Most new operations run well below that while the channel starts.
4. Certification and legal
Without CE, RoHS or the standard for your category, the product does not enter much of Europe. Lab tests, approvals and lab lead times belong in the calendar and in the cash. They are not “a later formality”.
If you import, the plan includes duty, import VAT at 21% if the goods enter from outside the EU, and who fronts that money. The VAT is recoverable; the cash gap is not. A product that works in the factory can fail at customs.
5. Channel, payment and cash
Amazon, your own site, retail, B2B? Each channel changes margin, stock and how long you wait to get paid. Amazon can sell fast and pay you later. A distributor may ask for 90 days. You, meanwhile, already paid the factory.
Working capital is the distance between paying and getting paid. In manufacturing, that distance eats projects that looked profitable on paper. The plan needs monthly cash flow for year 1, not EBITDA at year five.
A practical rule: split capex (moulds, tooling, tests) from working capital (stock, freight, VAT, ads). Mixing them is how you get to “the product is fine but there is no money”.
What business viability analysis means here
Viability is not “can it be made?”. It is “can it be made, sold and financed through the full cycle without breaking cash?”. Three questions:
- Is there demand at a price that holds the landed cost?
- Can you make that volume with a supplier who holds quality and lead time?
- Do you have (or can you get) the money for the gap between mould, first order and first payment?
If any answer is no, the plan is not ready to invest. It is ready to adjust product, channel or scope. That is also a result.
The full journey, from idea to listing, is in what it takes to launch your own product. The business plan is the numbered version of that journey.
How we use it
At Unicornio Azul the plan is not written to file a PDF. It is written to decide whether we industrialise, with which factory and at what margin. It is business opportunity analysis run through real costs.
If you are building one for your product, tell us. We will look at it the way we would if we had to order from the factory next week.
Informational article updated in September 2026. It does not constitute legal, tax or financial advice, nor a guarantee of viability. Regulatory and commercial conditions must be verified for each operation.
By Luis Chicharro
Shall we talk about your project?
If you are working on something similar, tell us about it and we will look at it from real experience, not theory.